
Initial Company Review
Company Description
Bloom Energy provides distributed energy technology solutions. It manufactures advanced and versatile fuel cell energy platforms and has two products:
1. Bloom Energy Server Fuel Cell System for generating electricity and
2. Bloom Electrolyzer for producing Green Hydrogen. Green Hydrogen can be used in the Bloom Energy Server to generate zero emissions electricity.
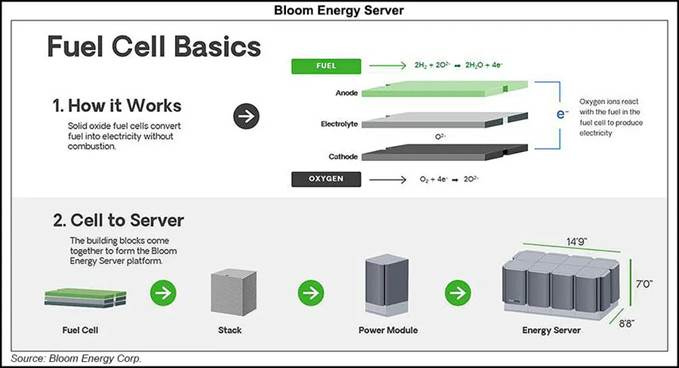
The Energy Server is a proprietary, high-temperature Fuel Cell that converts fuels-including natural gas, biogas, and hydrogen into electricity. It generates power in DC form and delivers output compatible with 800 VDC (Voltage direct Current) datacentre standards.
Bloom has approximately 1.4 gigawatts (GW) (enough to power 1.2 million homes) of Energy Server Fuel Cell systems deployed in more than 1,000 locations and nine countries.
The Bloom Energy Server system provides energy that is dependable, robust, environmentally friendly, and cost-effective.
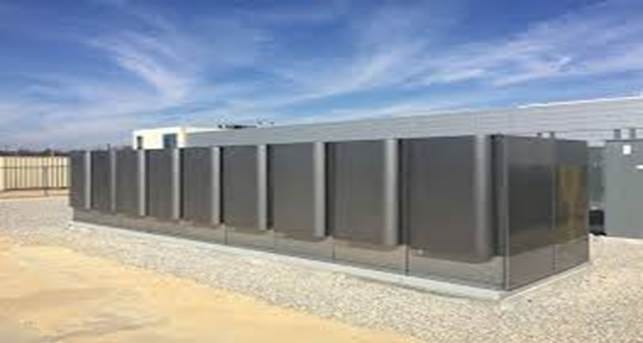
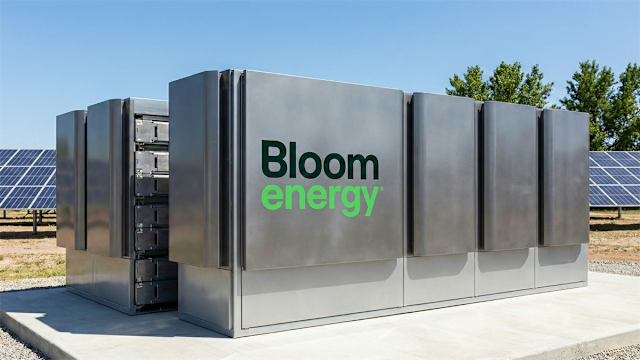
Installed Energy Server Systems
AI driving exponential Power demand.
As is well known, there is a huge capital expenditure boom in AI datacentres. The largest Datacentres now have 100,000 GPUs and require a 1 GW of power, enough to power a medium sized US city, like Philadelphia.
This year, the AI capex of the big 5 hyperscalers is likely to $600bn, perhaps the equivalent of about twenty large Datacentres. The growth has been exponential.
In 2022, the GPT-4 cluster consumed ten megawatts.
In 2024, the largest cluster required one hundred megawatts.
AI requires significant and continuous power. Reshoring across industrial sectors including semiconductors and advanced material is creating additional incremental demand for power in the USA.
Demand is strong. The supply is unresponsive in the short- term to medium term. The queue for generator interconnection to the Grid was 2300 GW at the end of 2024 with typical timelines extending many years. Power generation equipment manufacturers are only offering very extended timelines for delivery.
The ageing US Grid is used to decades of 3%-5% demand growth per annum and cannot grow fast enough to meet demand. It will take a long time increase capacity.
The utilities are responding. According to the Wall Street Journal, U.S. utilities are planning to spend an estimated $1.4trn or the next five years. That is up more than 20% from a year ago, when the companies planned to spend about $1.1 trillion over a five-year period. However, supply will take time to come online and will be short of the current or projected demand.
Renewables cannot provide continuous power even when coupled with batteries. The risk is power will fail when the sun does not shine or the wind does not blow. Additionally, the Tump administration has reduced incentives and tax breaks for investing in renewables.
Grid pressures and power shortages are biting constraints. They can determine where datacentres can be located. People increasingly do not want datacentres located in their neighbourhoods as they fear rising electricity bills.
The hyperscalers cannot wait. Some have signed purchase agreements with Utilities. They are also looking at onsite power. Onsite systems are flexible; customers control deployment timelines and can secure reliable baseload supply and reduce delays associated with lengthy permitting and interconnection issues.
This week Oracle announced it has extended a Strategic Partnership to deploy up to 2.8 GW to “Accelerate AI Infrastructure Build-Out” with Bloom Energy.
The Bloom Energy stock price rose on the news and this alerted us to the company. Bloom look well placed to rapidly provide on-site power to datacentres. This can be a temporary solution while the hyperscaler waits for the Grid to step up, or it can be more permanent.
Company Background
Bloom Energy was started by Aerospace engineer KR Sridhar. He used to work with NASA on technology to convert carbon dioxide into oxygen to support life on other planets or let humans breathe air on Mars.
After the Soviet Union fell and the space race slowed, NASA budgets shrank. Sridhar pivoted to providing clean energy technology for the rising global middle class.
In 2001, he co- founded Bloom to develop fuel cells to deliver cleaner, on-site, off-grid power. They anticipated that demand would be driven by the Energy Transition as governments pushed towards cleaner energy and lower carbon dioxide emissions.
What is a Fuel Cell?
A Fuel Cell is an electrochemical device that converts chemical energy directly into electricity — like a battery except it never runs out if fuel is continuously fed. There is no combustion, no moving parts, and no intermediate step of generating heat to spin a turbine.
All fuel cells share the same fundamental architecture: two electrodes (an anode and a cathode) separated by an electrolyte.
1. Fuel is fed to the anode (negative side) Hydrogen comes in at the anode where a catalyst strips the hydrogen atoms into protons (H⁺) and electrons (e⁻).
2. The electrons are forced to travel through an external wire to reach the cathode, and that flow of electrons is electricity.
3. Oxygen reacts at the cathode (positive side). Oxygen combines with the protons and the electrons to form Water.
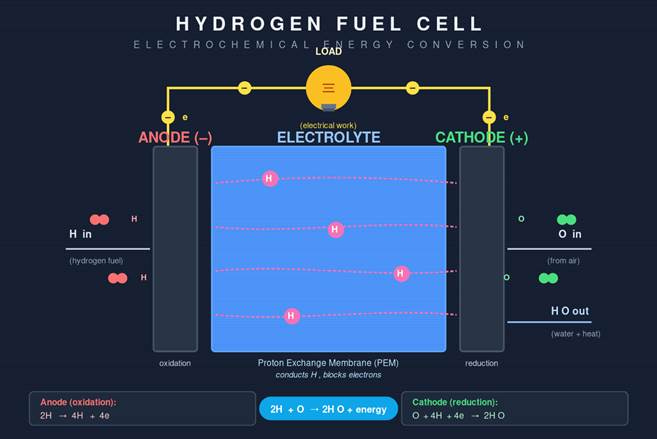
Hydrogen-ready fuel cells offer a solution for reducing greenhouse gas emissions and dependence on fossil fuels. Unlike traditional combustion engines, hydrogen fuel cells produce electricity through an electrochemical process that combines hydrogen and oxygen, with water and heat as the only byproducts. This process significantly reduces air pollutants, such as carbon dioxide and nitrogen oxide, which contribute to global warming and air quality issues.
Main Types of Fuel Cells
There are several types of Fuel Cells
PEM (Proton Exchange Membrane). PEM run on pure hydrogen, operate at ~80°C and are used in hydrogen cars (Toyota Mirai, Hyundai Nexo) and in portable power.
Solid Oxide (SOFC) — SOFC is Bloom Energy’s technology. It operates at extremely high temperatures (600–1,000°C), which allows it to internally reform natural gas or biogas into hydrogen. It is a very efficient (50–60%+) process and is best suited for stationary power generation. SOFC is a proven technology that has been developed by Bloom over twenty years.
Advantages Over Conventional Power Generation
Fuel cells have no combustion, so they produce minimal Nitrous Oxide, Sulphur Oxide or particulate emissions.
They operate silently with no moving parts, which makes them ideal for datacentres and urban deployment.
They are significantly more efficient than gas turbines (which typically achieve 35–45% efficiency vs. 50–60%+ for SOFCs).
They also produce usable waste heat, enabling combined heat and power (CHP) configurations that can push total energy utilisation above 80–90%.
Relevance to AI Datacentres
Datacentres need power that is dependable, fast to deploy, and not dependent on Grid capacity. Fuel cells meet all the requirements..
Fuel cells have existed for years, but they have lacked mainstream adoption because due to high manufacturing costs. They require expensive precious metals, corrosive acids, or hard-to-contain molten materials.
Bloom’s solid oxide fuel cells use lower-cost ceramics—not precious metals—and they provide much greater electrical efficiency, operating at temperatures above 600 degrees Celsius.
A fuel cell can be set up on campus, bypassing lengthy grid interconnection approvals, and it may start operating within months.
As many 1 GW plus AI campuses are planned, fuel cells are increasingly seen as a critical bridge technology.
Bloom Energy’s Solid Oxide Fuel Cells (SOFC) have been used in numerous settings, including healthcare, datacentres, essential manufacturing, retail, and more.
The environmental case for Fuel Cells is even stronger if the feedstock is Green Hydrogen
There are multiple methods for producing green hydrogen. Bloom has produced an innovative electrolyzer for producing Green Hydrogen. An electrolyzer is the reverse of a fuel cell.
Where a fuel cell combines hydrogen and oxygen to produce electricity and water, an electrolyzer uses electricity to split water (H₂O) into hydrogen and oxygen. It is the primary technology for producing green hydrogen — hydrogen made using renewable electricity.
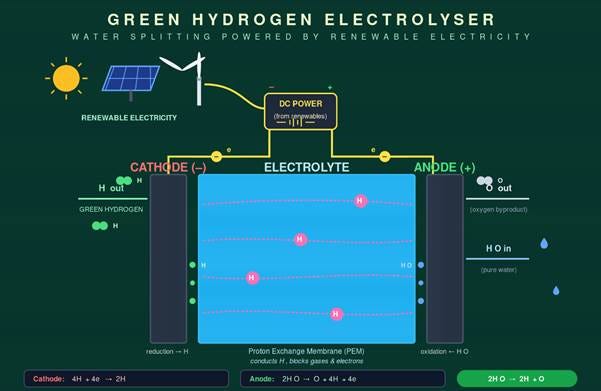
The vast majority of Bloom’s installed base currently runs on natural gas. The cells reform the gas internally, extracting hydrogen ions and converting them electrochemically to electricity — no combustion involved.
However, the SOFC technology is inherently fuel-agnostic. Customers can start to switch from natural gas to more efficient hydrogen today and switch fully to hydrogen as the supply scales up.
Bloom’s “fuel-agnostic” architecture is a key competitive differentiator. Unlike Proton Membrane Exchange (PEM) fuel cells that require pure hydrogen, Bloom’s boxes work on today’s gas infrastructure while offering a credible decarbonization pathway.
This explains why Bloom has become a favoured solution for AI datacentres — Microsoft, American Electric Power, and others have signed large agreements.
The sales strategy is simple strategic positioning is essentially: sell natural gas-powered fuel cells now, transition to hydrogen later — keeping them relevant across the entire energy transition.
The Bloom Electrolyzer delivers hydrogen solutions by utilising the solid oxide platform that also powers its Energy Server systems.
Fuel cells are modular, allowing users to adjust output based on demand. Once Grid power is available at the original site, they may be transferred to other datacentres as needed.
Fuel cell microgrids qualify for tax credits in Trump’s One Big Beautiful Bill.
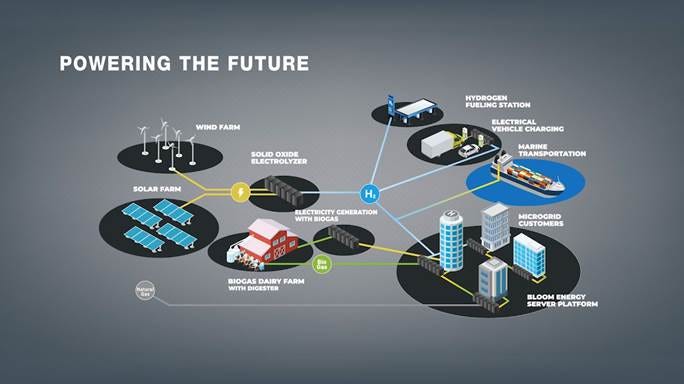
In terms of the cost, they are equivalent to combined-cycle gas turbines, but fuel cells can come online more quickly and produce power more cleanly.
Bloom has a multitude of factors working to its advantage, including a head start on competitors, a domestic manufacturing chain when the US administration is pushing onshoring and tariffs, and an early bet on fuel cells for “stationary power” while potential rivals focused on fuel cells for the transportation sector.
Financial Summary
Revenues
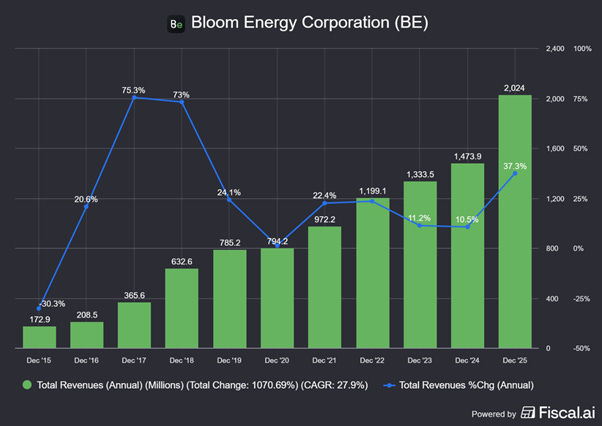
Bloom’s revenues have grown at a CAGR of 28% in the last ten years. The robust growth in the last year has been due to AI datacentre demand.
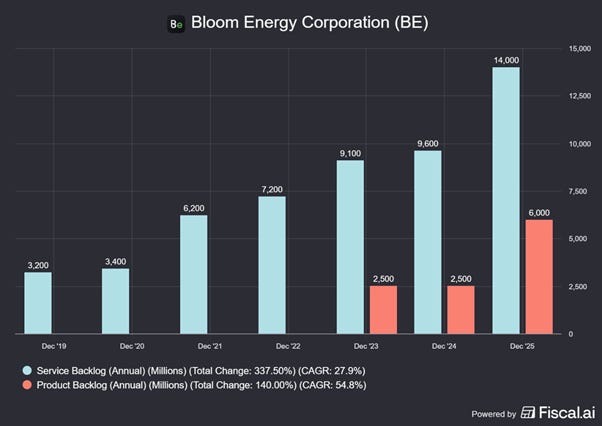
The company has signed big data center deals with Oracle, American Power (AEP), Equinix and Brookfield Asset Management. The latter is a $5 billion partnership to power AI factories globally, including Europe. As a result of these orders, Bloom entered 2026 with a total backlog approaching $20 billion. (6X current revenue run rate). Bloom is effectively “sold out” through 2026–2027, de-risking the earnings profile.
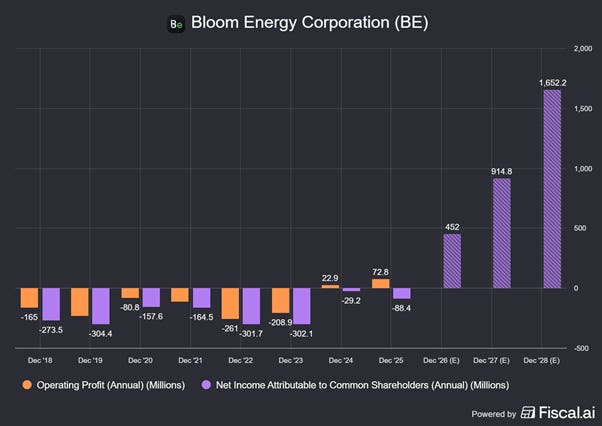
Bloom has been loss making for a long time while it developed its technology and looked for buyers. It has posted positive operating profit for two consecutive years.
Analysts are forecasting positive profits at the net level from this year (see chart above).
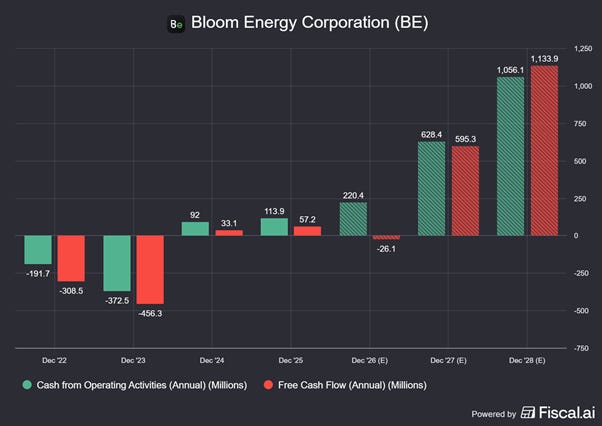
The company is expected to generate significant cash from 2027 onwards (see chart above). It has reported two consecutive years of positive free cash flow. In 2025 operating cash flow was $220mn.
These figures indicate the company is now on track for sustained profitability and positive cash flow.
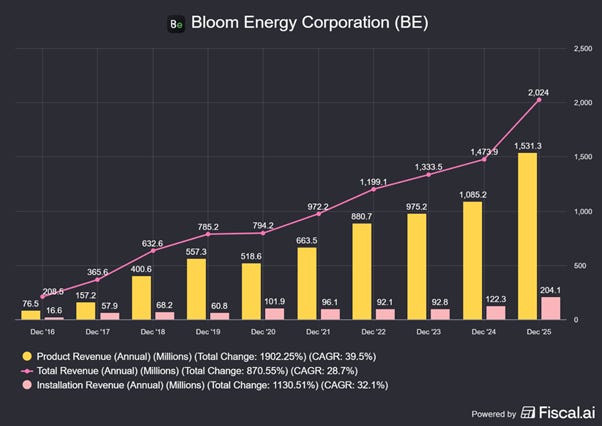
Revenue Mix.
Bulk of the revenue (75%) comes from selling products (Energy Servers and Electrolyzers
The company also earns revenue from installation (10.1%) and long-term maintenance (11.3%). As the pace of new deployment increases, revenue from both these sources will increase and the latter will be a recurring revenue.
Types of customers
AI & Datacentres: Bloom Energy had one hyperscaler/ neo cloud customer a years ago. They now have six. The order from Oracle has increased significantly, as noted above.
Commercial & Industrial (C&I): There has been robust growth in orders in the C&I segment. Companies reshoring production back to the US in semiconductor and advanced manufacturing is driving demand for “quick time to installation” power.
Utilities also buy to plus gaps in their own capacity.
There has been an interesting geographic shift in demand: Over 80% of the US backlog is now in low-cost power states outside California and the Northeast, proving Bloom Energy is cost-competitive even in areas with low power costs.
Geography of Demand
The US is the largest market. South Korea is the second largest market. Bloom is looking to expand in Europe and the Rest of Asia.
Margins
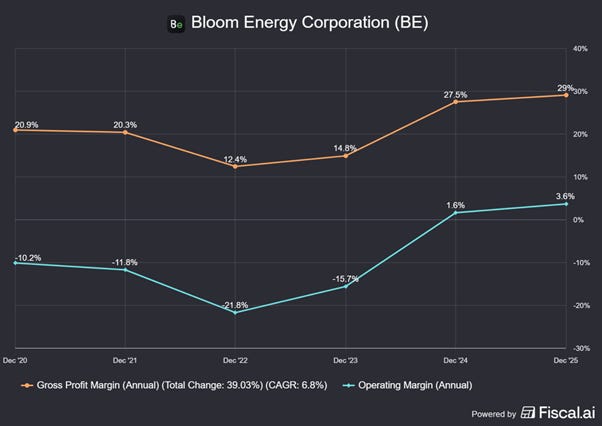
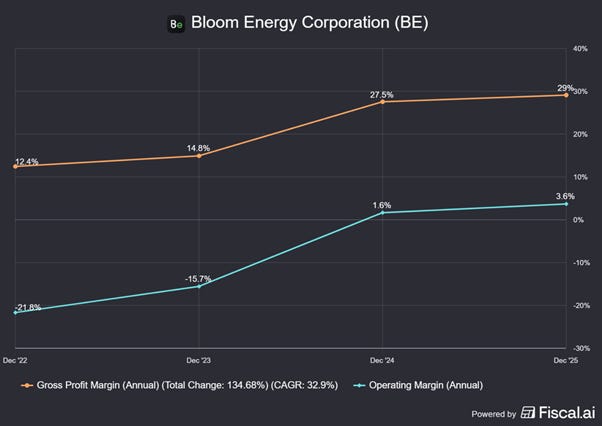
Margins have improved as the scale of the company has increased. Gross margins have risen by 40%. The company has reported positive operating margins over the past two years, and projections indicate these margins will continue to grow.
Balance Sheet Strength and Free Cash Flow Quality
The company has been engaged in product development for the past two decades. There was an extended period where money was flowing out while revenues were lower. As a result, the balance sheet experienced some strain.
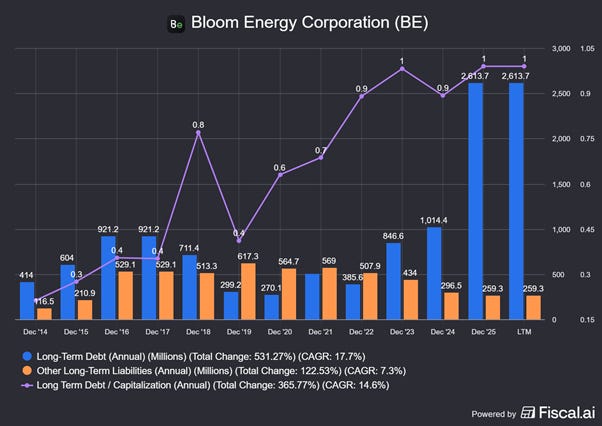
There has been a steady increase in debt and leverage as shown in the chart above.
A recent debt refinancing reduced the company’s risk. Bloom issued a $2.5 billion 0% convertible bond issuance used in November 2025 to refinance higher-coupon convertible debt. The maturity date is in 2030. By that time, operating and free cash flows should be much higher. It should be able to redeem the Convertible (if not converted into equity) or it can be refinanced.
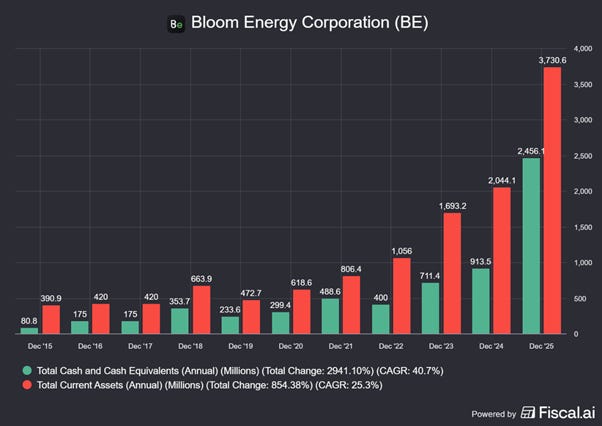
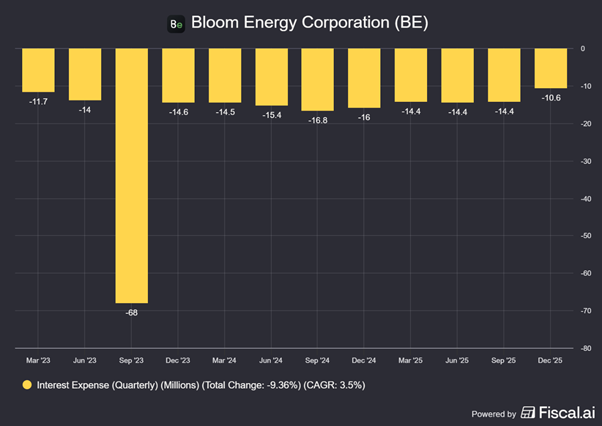
The issuance of Convertible Bonds has increased total cash and cash equivalents, and the reduction in interest expense (as shown in the chart below) is expected to persist.
The Road Ahead
Bloom Energy faces a situation of accelerating demand. To scale up to meet it, they will
must expand their manufacturing and sales capacity.
boost operations and installations, infrastructure and accelerate technology development.
build long term partnerships with capital providers.
Partnerships
SK Ecoplant of South Korea has been a strategic partner since 2018. They have committed to purchase Energy Servers and established a joint venture for assembly of Energy Servers for South Korean Market
Bloom Energy started a strategic partnership with American Power (AEP) in 2024, under which AEP will buy up to 1GW for deployment in AI datacentres.
In August 2025, Bloom Energy entered a strategic partnership with a prospective financing framework of up to $ 5bn over five years. Brookfield is an investor in AI Datacentres.
R&D
Bloom Energy has built a team of scientists and technology experts over ten years. Experts in Material Science and in Electrical, Chemical, Mechanical, Civil and Nuclear Engineering and includes 62 PhDs. Over the years, the team has reduced costs, increased system output and fuel cell life by over two and a half times.
The company has spent twenty years developing its technology. competitors such as have focused on fuel cells in transportation. It has over six hundred patents.
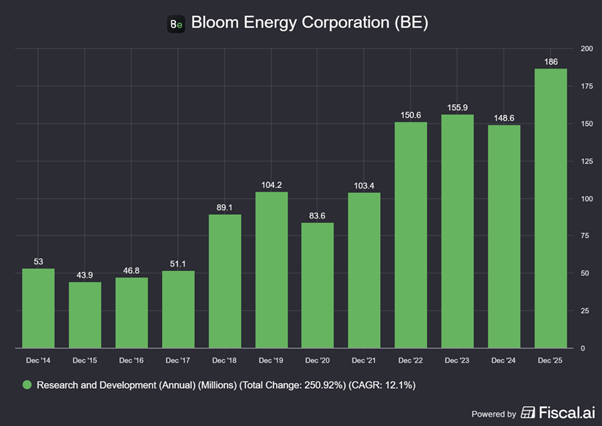
Research and development costs have been recorded as expenses in the profit and loss account when incurred. This is conservative accounting.
Employees
At end December 2025, they have 2214 full-time employees. 1752 are in the USA. 395 in India and 67 are elsewhere.
Competition
Bloom Energy has a few competitors. These include FuelCell Energy, Doosan Group’s HyAxiom, and Plug Power. They offer different variations on the technology, but they have not yet scaled up as much as Bloom.
Bloom also competes with Conventional Power generating companies.
The company believe their offering can compete effectively due to greater reliability, faster deployment, higher efficiency, and alower emissions profile.
On deployment speed, Bloom delivered an AI factory order in 55 days against a 90-day commitment. This compared with 2plus years for utility grid upgrades.
Another competing technology is small modular nuclear reactors. These offer some attractive features, but development times tend to be protracted.
Manufacturing Capacity
They have two manufacturing facilities: in Fremont, California and Newark, Delaware.
They will increase the capacity at the Fremont facility from 1GW to 2 GW to meet Orace /AEP demand.
Shares Outstanding
The numbers of share outstanding has increased rapidly and this may continue if recently issues convertible securities converted into equity in three or four years.
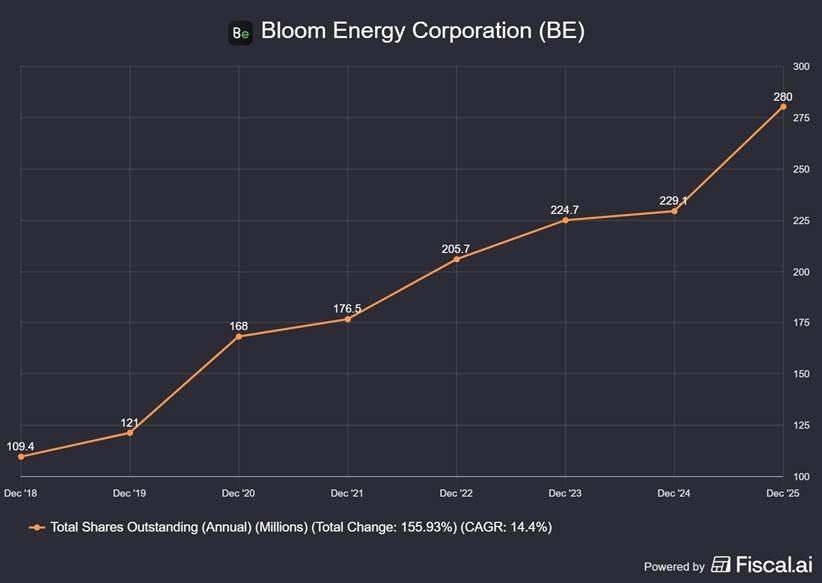
However, as the company generates more operating cash and free cash flow, it will not need to issue more shares and can think about deploying excess cash to buying back shares.
Valuation
The share price has risen more than 10x in the last three years.
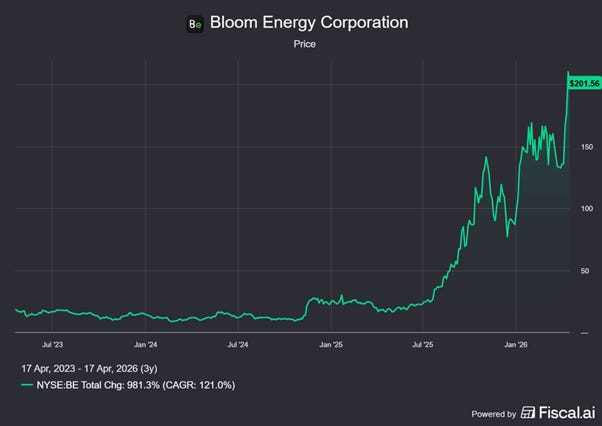
Therefore, valuations have risen strongly. For example, the price to sales ratio has risen strongly.
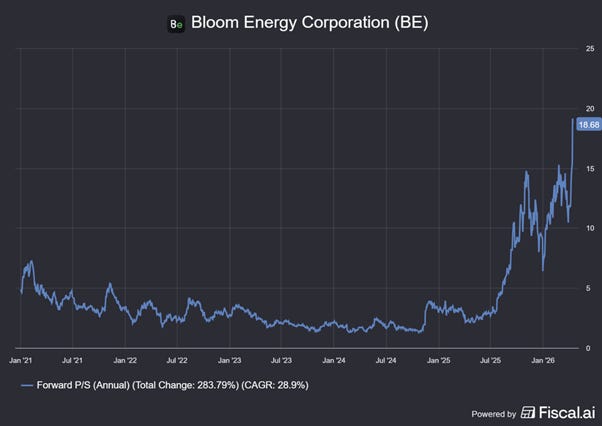
The Price to Operating Cash Flow ratio has also risen greatly.
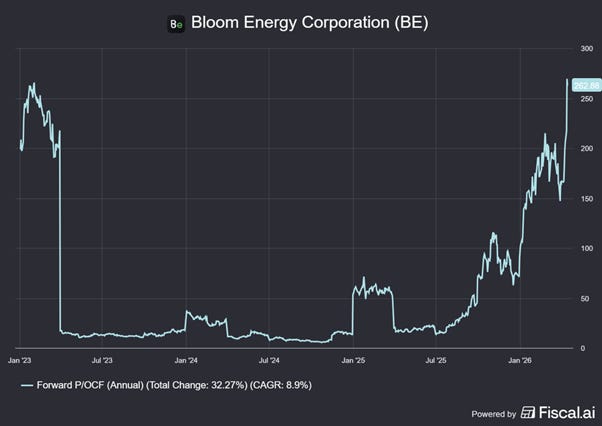
Markets are excited about potential strong AI demand. The markets has realised the company is at a pivot point with AI demand likely to lead to significantly higher revenues and free cash flows down the line.
Give this, the company will look expensive on conventional valuation measures.
The BE shares are currently trading at 1-year forward P/E model of 114X. It shares at a 1-year forward P/FCF model of 1062X.
Markets are expecting an explosive growth in Earnings and Free Cash Flow (FCF).
The Analysts Consensus for Free Cash Flow for FY 28 is ~ US $ 1.1bn. At the current market cap of ~$ 60bn, this implies a two-year forward P/FCF Ratio of 45X.
Conclusions
It is hard to say whether this is expensive as it assumes that BE will continue to grow very aggressively for the next five or six years. We lack the expertise to make long-term forecasts.
Out general approach suggests that this stock should go into what the late Charlie Munger used to call the “too difficult category” which should not be invested.
However, we will break our own rules and allocate a nominal 1% of the portfolio to Bloom Energy. We recognise this is an expensive and risk stock but are excited by the demand growth potential due to the AI boom.
If the stock fall much lower and our thesis remains intact, we would be ready to add to the position.
Please note that this information does not constitute investment advice, and individuals are advised to conduct comprehensive research on the stock prior to making any capital commitments.
Time-to-power advantage is critical. The 55-day deployment speed for AI factory orders you cited is the true moat here, more important than hardware costs given the current utility grid backlog. Bloom’s ability to bypass the interconnection queue is the real catalyst for these 2.8 GW hyperscale deals.